
When You’re Just Short of the Rule
We know how frustrating it is to find the perfect rental unit, only to fall short of a strict income multiplier. Standard leasing rules often demand an income of three times the rent. This rigid metric easily sidelines self-employed business owners and homeowners transitioning to a temporary rental.
Our clients frequently ask for options if you dont meet apartment income requirement policies.
Finding a workaround requires understanding exactly how property managers calculate risk. You can often bypass these hurdles by looking at apartments with lower income requirements before paying extra fees. We designed this guide to compare your main options so you can make a confident decision.
The Four Main Paths
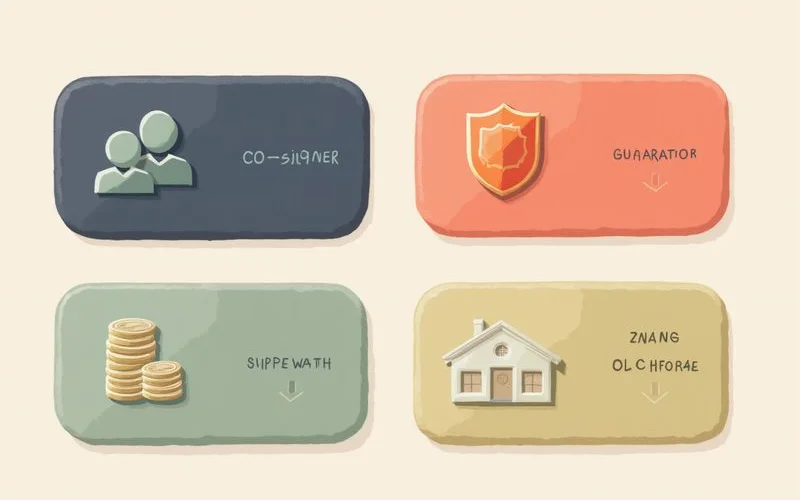
A common approach is leaning on a third party, but upfront cash solutions also work well. Each choice carries different financial weights for a business owner managing cash flow. Our team sees four reliable methods to secure an approval when your base income falls short.
| Option | How it works | Typical trade-offs |
|---|---|---|
| Co-signer | Someone signs the lease with you and shares responsibility | They are legally responsible for rent and must meet strict income rules |
| Guarantor | Someone promises to pay if you default, without living there | Corporate guarantors usually charge a non-refundable premium fee |
| Additional deposit | You pay a larger security deposit up front | State caps like California’s AB 12 strictly limit the maximum amount allowed |
| Lower-criteria property | You apply where the income rule is 2x or 2.5x | You might have fewer property choices in your preferred neighborhood |
Comparing the long-term cost is essential before signing anything. Properties also charge a one-time risk fee instead of utilizing standard methods. We remind you that these premiums are usually not refundable, so read the terms closely.
Co-Signers
A co-signer takes on equal legal responsibility for the rent. This person shares the financial burden if you miss a payment. Our experience shows that landlords scrutinize these helpers heavily before granting an approval.
The average US credit score sits around 713 in 2026, but managers demand higher scores from co-signers. They typically require the co-signer to have a FICO score of 700 or above and an income at least four times the rent. We advise preparing your personal contacts for a hard credit inquiry to prevent awkward conversations later.
Comparing an apartment guarantor vs cosigner reveals that a co-signer has the legal right to live in the unit. This makes it a popular option for homeowners renting a place for their college-bound children. Our best advice is to have a candid conversation about risk before submitting the paperwork.
Guarantors
A guarantor promises to pay the landlord if you default, but they do not have the right to occupy the property. They strictly act as a financial backstop for the lease. We frequently see business owners utilize third-party guarantor services when personal contacts are unavailable.
Individual Guarantor Requirements
Landlords often require a personal guarantor to prove an income of five to six times the monthly rent. It takes careful planning to gather those financial documents quickly. Our experts suggest verifying exactly what tax returns or bank statements the property requires upfront.
Corporate Guarantor Services
Institutional companies like TheGuarantors or Insurent step in to back your lease for a fee. These corporate guarantors generally charge a non-refundable upfront premium. We track these costs, noting that this fee usually ranges from 70% to 110% of one month’s rent.
Property managers favor these services because they streamline the risk management process. You must confirm that your specific building accepts the exact guarantor company before applying. Our team always reminds applicants that these premiums do not count toward your security deposit at move-out.
Additional Deposits
Offering a larger upfront cash deposit is a direct way to secure additional deposit apartment approval. This strategy works well if your business holds strong cash reserves but shows lower net monthly income. We closely track the evolving legislation around security deposits across the US.
State laws dictate exactly how much extra cash a landlord can request. For example, California enacted AB 12, which strictly caps security deposits at one month’s rent as of mid-2024. Our team strongly recommends checking your local state caps before offering extra cash.
A landlord in a capped state cannot legally accept a three-month deposit to offset your lower income. The law penalizes property owners who exceed these specific deposit limits. We suggest asking three distinct questions to protect your cash reserves.
- How much extra cash is required by the leasing office?
- Is the entire amount refundable at move-out, and under what specific conditions?
- Is this classified as a deposit or a non-refundable risk fee?
Many property managers treat this extra cash as a standard refundable deposit, but some try to label it as a fee. Always verify the terminology in writing before signing the final contract. Our advisors remind clients that documenting the terms protects your business cash flow.
Lower-Criteria Properties
Focusing your search on properties with lower income multiples eliminates the need for expensive workarounds. Finding a building that requires 2x or 2.5x the rent saves you from paying third-party fees. We often steer business owners toward different property classes to find these favorable terms.
Large, institutional Class A apartment complexes usually strictly enforce the 3x income rule. Independent landlords managing Class B or Class C properties tend to offer much more flexibility. Our guide on what 3x the rent means explains the math behind these different requirements.
Mom-and-pop property owners will often weigh your overall business cash flow and savings instead of relying solely on a W-2. Applying to these flexible properties is typically the most cost-effective solution available. We highly recommend confirming the criteria before paying any application fees.
Confirm before you apply
Whether a property offers any of these options must be confirmed with that property. Policies differ and can change.
Questions to Ask the Property
You must ask the leasing office highly specific questions about their approval policies before paying an application fee. Getting these answers in writing prevents costly misunderstandings down the line. Our experts suggest bringing a prepared checklist when touring any new potential rental property.
Leasing agents handle hundreds of applications and might forget to mention a specialized alternative program. Asking the right questions forces them to clarify their exact underwriting standards. We use the following list to get clear answers from property managers.
- If my business income falls below your strict requirement, what alternative approvals do you offer?
- Do you accept individual co-signers, and do they need a 700+ FICO score?
- Are specific third-party guarantor services like Rhino or TheGuarantors integrated into your system?
- Do you offer approval with an extra deposit, and does my state cap that amount?
- Can all household members combine their varied income streams to meet the multiple?
Protecting Yourself and Your Helper
Treating a lease guarantee as a serious legal liability protects both your personal relationships and your financial standing. Your helper needs to understand the exact duration and scope of their financial commitment. Our legal researchers note a major point of confusion surrounding modern alternative deposit products.
Products structured as surety bonds, like Rhino, protect the landlord’s revenue, not your personal liability. If a claim is paid out, the third-party company will still legally pursue you for the damages. We advise all clients to read the fine print of any third-party guarantee together with their helper.
- Read the guarantee together. Know exactly what the helper is responsible for: rent only, or also damages and fees?
- Ask about duration. Some guarantees end with the original lease, while others continue through renewals.
- Keep them informed. If you fall behind, tell your helper early rather than letting them hear it from the property.
- Pay on time. A strong payment record may let you renew later without a guarantor.
- Read third-party guarantor terms closely. Fees are usually non-refundable, and some services can seek repayment from you if they pay the landlord.
Taking careful, dated photographs at move-in protects your extra cash investment over the long term. You need to document the exact condition of the unit before moving your furniture inside. Our team recommends emailing these dated photos to the landlord immediately to create a permanent record.
Choosing the Right Path
Selecting the optimal workaround depends entirely on your available cash reserves and personal network. You must run a total cost analysis for the entire lease term before making a final decision. We use a simple framework to help clients compare these distinct options.
- Someone willing and able to help? A co-signer or guarantor avoids corporate fees entirely.
- Savings but modest monthly income? An additional deposit works well if state laws allow it.
- Neither? Focus your search on independent properties with lower criteria or a different area entirely.
Comparing the non-refundable premium of a corporate guarantor against the refundable nature of an extra deposit is crucial. You should calculate the true out-of-pocket cost for year one. Our final piece of advice is to verify all totals before submitting a formal application.
Let Us Narrow It Down
Vetting hundreds of properties to find their specific income policies consumes valuable business hours. Getting expert help streamlines your search and targets the right property managers immediately. We know that your time is better spent running your business or managing your home.
Researching individual community criteria and verifying their alternative approval options is extremely tedious. You can save hours by utilizing a specialized apartment locator service. Our team provides a Request a researched list option built for your specific budget and household size.
This research identifies communities that align with your unique financial profile. The list highlights properties known to accept third-party guarantors or structured extra deposits. We do not guarantee final approvals, as every property manager executes their own final screening process.
Each property applies its own specific criteria and makes independent leasing decisions. Submitting your details to get a customized list is the best first step. Our goal is to give you the data needed to secure your next home confidently.