
Two Numbers, Two Purposes
We notice that understanding the minimum income requirement vs maximum income limit is a major challenge for many applicants and property investors alike. Apartment eligibility usually involves two critical income numbers that serve entirely different goals.
One acts as a floor, which dictates the minimum income a property requires, while the other is a ceiling that caps the maximum income allowed for an affordable unit.
According to early 2026 data from CoStar Group, the national rent-to-income ratio sits at 23.3%. Property managers enforce an income floor to ensure tenants can comfortably handle that financial burden without risking default.
This dynamic explains why you might be told you earn too little at one place and too much at another.
We recommend reviewing our targeted research on lower minimum-income apartments if you are struggling with steep floor requirements. Let’s explore how these limits interact, what they measure, and how to define your eligibility window.
Side-by-Side Definitions
Minimum and maximum income criteria measure completely different aspects of your financial profile. The minimum requirement checks if your gross pay covers rent, while the maximum limit ensures the unit goes to someone within a specific low-income bracket. We designed this comparison table to highlight exactly where these two standards diverge.
| Feature | Minimum income requirement (floor) | Maximum income limit (ceiling) |
|---|---|---|
| What it checks | Whether you earn enough relative to rent | Whether you earn little enough for a restricted unit |
| Who sets it | The property’s specific screening criteria | A housing program like HUD or LIHTC |
| Typical form | A multiple of rent, often 2.5x to 3x, or a fixed dollar amount | A dollar limit determined by household size and AMI tier |
| Where it applies | Market-rate and many affordable properties | Income-restricted and tax credit units |
| Can it change? | Yes, at the property manager’s discretion | Yes, typically updated every spring when HUD releases new figures |
Understanding these distinctions is crucial before you pay a non-refundable application fee. Properties using standard management software like Yardi or RealPage will automatically run your numbers against both criteria during the background check.
How One Property Can Have Both
Searching for income floor and ceiling apartments often leads applicants to subsidized housing programs. The government sets the maximum limit, but the property management business still establishes a minimum threshold to ensure reliable cash flow for fixed rent amounts.
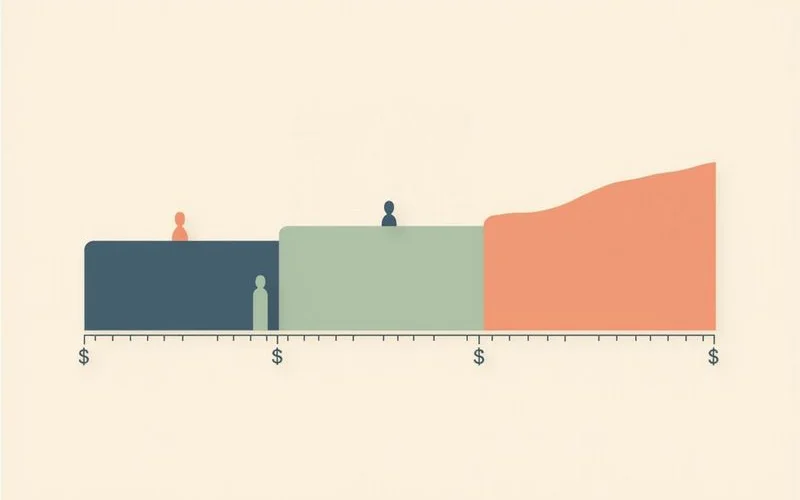
We frequently see this dual-requirement in Low-Income Housing Tax Credit (LIHTC) communities, which account for over 3.5 million affordable units nationwide. The federal program strictly dictates the maximum income ceiling to reserve housing for those in need. Meanwhile, the property manager sets the minimum income floor because the discounted rent is still a fixed monthly obligation.
The Business Reality of Rent Minimums Affordable housing programs mandate the discounted rent amount, but the property still faces rising insurance, maintenance, and utility costs. Landlords rely on the minimum income floor to guarantee the business can collect that fixed monthly rent.
Your total household income needs to land perfectly inside that eligibility window. You will fail the financial screening if your earnings dip below the floor. You will be disqualified from the restricted unit if your pay exceeds the ceiling limit.
An Example of the Resulting Range
Calculating your specific eligibility range requires comparing the landlord’s minimum multiplier against the government’s maximum cap. We will look at a hypothetical scenario to demonstrate how these two standards interact in practice.
Let us use straightforward, neutral numbers for a clear comparison:
- A restricted two-bedroom unit rents for $1,000 a month.
- The property’s minimum floor requires 2x the rent, which equals $2,000 per month or $24,000 a year.
- The program’s maximum ceiling for a household of three at that specific tier is set at $45,000 a year.
A three-person household earning between $24,000 and $45,000 annually fits perfectly inside both rules. An applicant earning $20,000 falls below the required floor and faces immediate rejection. A family earning $50,000 lands above the legal ceiling and cannot secure the subsidized rate.
Use real, current figures
This example is purely illustrative to explain the concept. Real limits depend on the specific program, your geographic area, household size, and the current effective year. We strongly advise confirming both exact numbers directly with the leasing office.
For context, HUD updated the national median family income benchmark to $107,900 for 2026, and local maximums scale up or down from that baseline. You must convert all your income to an annual gross figure to make an accurate comparison.
Finding Your Window
Locating your exact eligibility window takes a bit of proactive research before you ever submit an application. You need to gather the official government limits for your city and the specific screening criteria used by the property manager.
We use a simple, five-step verification process to ensure applicants do not waste money on application fees.
- Find the ceiling. Look up the current income limit for the property’s geographical area, the specific unit’s AMI tier, and your exact household size. Our comprehensive guide to AMI-based limits explains exactly how to read these complex government tables.
- Verify the effective date. HUD released its 2026 income limits in May 2026, so make sure you are not looking at outdated figures from the previous year.
- Find the floor. Ask the property manager for their specific minimum-income multiplier and ask exactly what types of income they accept.
- Compare your gross annual income against both the floor and the ceiling.
- Confirm everything. Always verify these boundaries directly with the property staff before running your credit.
Property management software usually calculates these ratios using your gross income before taxes. Using your take-home net pay is a common mistake that will throw off your entire calculation.
When the Window Is Narrow or Closed
Your household income will sometimes fall completely outside the required range, or the gap between the floor and ceiling might be impossibly narrow. Do not give up immediately if your initial calculation shows a mismatch. We always encourage applicants to explore a few strategic alternatives when they miss the standard window.
Consider these backup options if you fail the initial income test:
- Request a different unit size. Switching to a one-bedroom instead of a two-bedroom alters the rent amount, which subsequently lowers the required income floor.
- Ask about a different AMI tier. Many LIHTC properties offer multiple tiers within the same building, such as units reserved for 50% AMI versus 60% AMI.
- Seek a relaxed minimum requirement. Look for a landlord who uses a 2x or 2.5x multiplier instead of the strict 3x standard.
- Pivot to market-rate housing. You must shift your search to conventional, non-subsidized apartments if your earnings consistently sit above the maximum ceiling.
- Leverage your housing voucher. Section 8 voucher holders should always ask how the minimum rule is calculated.
Our best insider tip involves that final point regarding vouchers. Federal guidelines and many local laws state that landlords should only apply the rent-to-income multiplier against your specific portion of the rent, rather than the total market price. This adjustment dramatically lowers the minimum floor for voucher holders.
Common Mix-Ups to Avoid
Misinterpreting the financial rules is the most common reason applicants face unexpected rejections. You can save yourself significant time and frustration by double-checking your math against the industry’s standard screening practices. We see renters make the same calculation errors year after year.
Here are the most frequent pitfalls you need to avoid:
- Comparing monthly income to a yearly limit. Maximum limits are almost always published as annual figures, while minimum floor rules are quoted as monthly rent multipliers. You must convert both numbers to the same yearly or monthly time frame before comparing them.
- Using your take-home net pay. Standard tenant screening, including services run through LeaseRunner or TransUnion, uses your gross income before taxes. Using your net pay will make you falsely believe you fall below a required floor.
- Using the wrong household size. The government ceiling depends entirely on how many people live with you. A household of four has a significantly higher income limit than a household of two.
- Assuming last year’s limit still applies. Maximum limits receive annual updates based on fresh economic data. The 2026 average limit increase was 3.4%, so relying on old charts will give you an inaccurate ceiling.
- Assuming every property uses the same floor. One community may require 3x the rent, another might accept 2.5x, and a third might demand a flat dollar amount. Receiving a rejection at one property does not mean you will fail the screening everywhere else.
- Forgetting the critical voucher question. If you carry a Housing Choice Voucher, always ask the leasing agent how they apply their minimum floor. They should evaluate your financial strength based strictly on your personal share of the rent, not the gross total.
Avoiding these common calculation mix-ups gives you a much clearer picture of where you actually stand. We strongly suggest confirming these details over the phone before you formally apply.
What Your List Shows
Your personalized list displays the known minimum-income criteria alongside any verified maximum income limit apartment details to streamline your search. We pull this data together to give you a clear, side-by-side view of your true eligibility window.
If public records exist, the list includes the specific data points along with their source and timestamp. Any missing metric is clearly marked as needing manual confirmation.
We want to remind you that each apartment community formally verifies its own applicant data and makes its own final approval decisions.
Reach out to the property managers directly to finalize your timeline, and best of luck finding your next home.